A Regional Bell Operating Company (RBOC), also called a Baby Bell, is one of the seven regional holding companies created when AT&T’s Bell System was broken up under a US antitrust settlement that took effect in 1984. Each RBOC took ownership of several of the 22 Bell operating companies (BOCs), the local phone companies that provided local service and held the local network: central offices, copper lines and rights-of-way. Through later mergers most RBOCs and their operating companies are now part of AT&T, Verizon and Lumen, but the term still matters to buyers because the networks the Bell companies built carry a large share of US business last-mile connections.
At a glance
- The seven original RBOCs were Ameritech, Bell Atlantic, BellSouth, NYNEX, Pacific Telesis, Southwestern Bell (later SBC) and US West.
- Each owned a group of the 22 Bell operating companies; those operating companies, or their successors, are the incumbent local exchange carriers (ILECs) in their territories.
- Mergers since the 1990s folded most of them into today’s large national carriers; some local territories were later sold to other companies.
- Many business circuits sold by other providers still use the incumbent’s last mile, which affects lead times, repairs and diversity.
- The former Bell operating companies’ networks are where much of the US copper retirement is happening.
What problem it solves
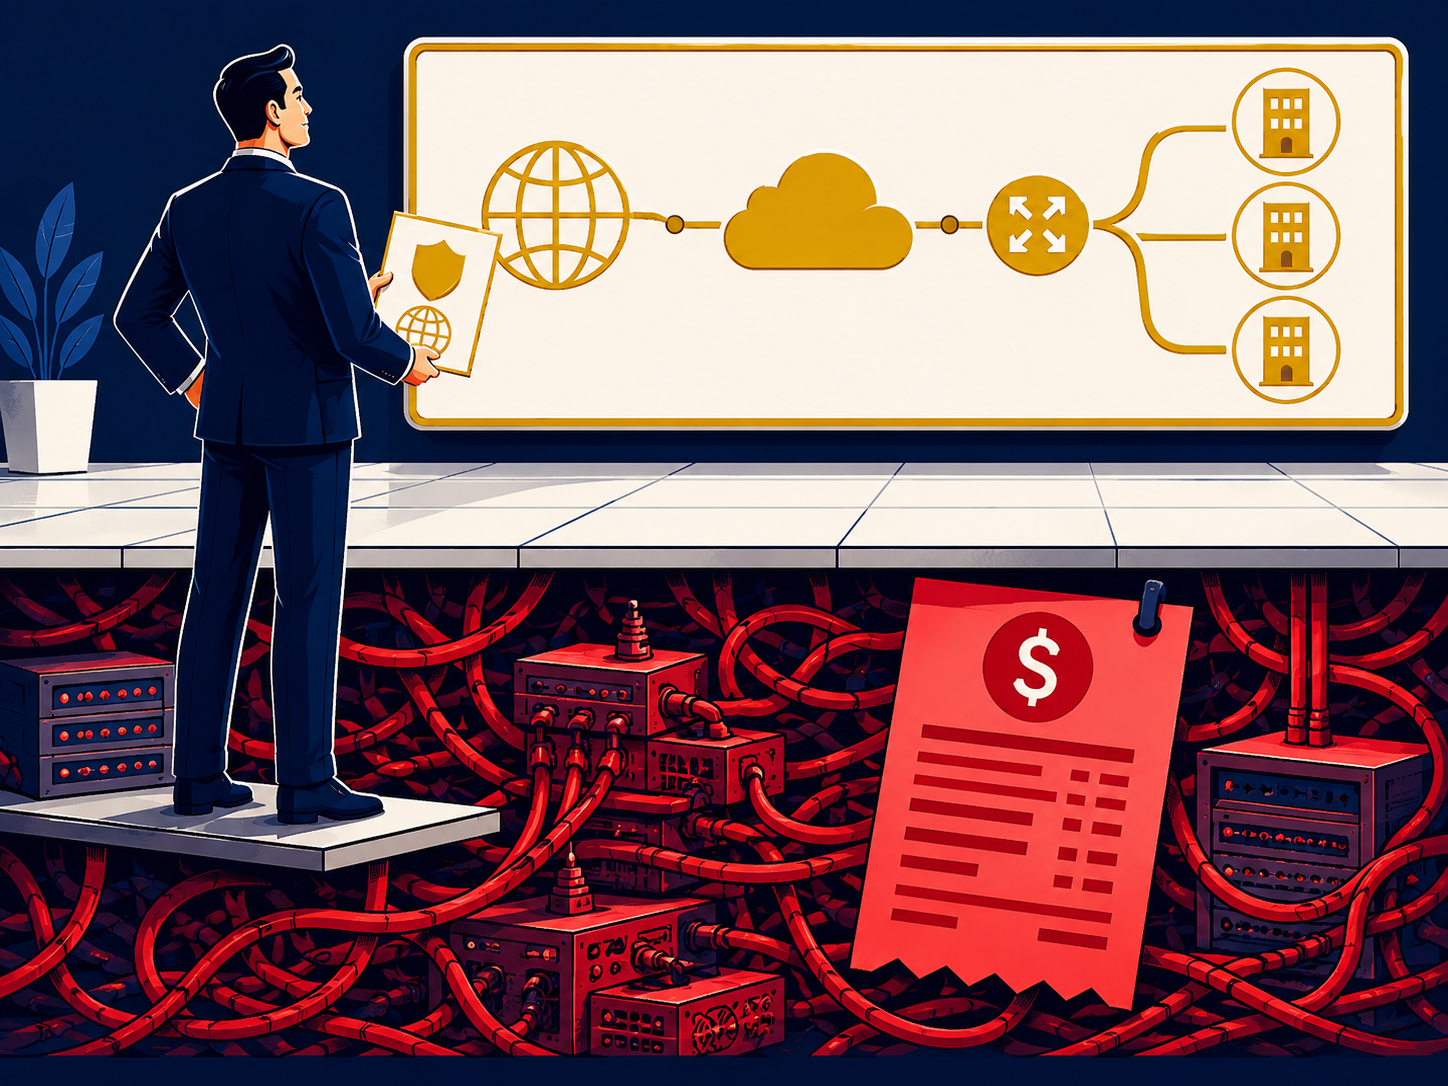
RBOC is a label, not a product, but understanding it solves a practical problem: knowing who actually owns the cable into your building. A quote may come from a national carrier, a competitive provider or a managed service provider, yet the physical connection for the final stretch may still be the incumbent’s copper or fiber. That owner decides what can be delivered, how long construction takes, who rolls a truck when it breaks and whether a “second” circuit is really separate from the first.
How it works
Breakup and territories. Before 1984, AT&T owned most local and long-distance service in the US through the Bell System. The antitrust settlement separated the 22 local Bell operating companies from AT&T and grouped them under seven regional holding companies, the RBOCs, each covering a defined region. The operating companies kept providing local service and owning the local network. Long-distance and equipment stayed with AT&T, and for years the RBOCs faced restrictions on entering those markets.
Competition. The Telecommunications Act of 1996 opened local markets to competitive local exchange carriers (CLECs), which could interconnect with the incumbent, lease parts of its network, resell its services or build their own. It also set conditions under which the Bell companies could offer long-distance. The obligations to lease network elements to competitors have been narrowed over time by regulators, so what competitors can obtain from the incumbent today varies by service and location.
Consolidation. Through the late 1990s and 2000s, SBC acquired Pacific Telesis, Ameritech, AT&T and BellSouth and took the AT&T name; Bell Atlantic merged with NYNEX and GTE to form Verizon; US West became part of Qwest, then CenturyLink, now Lumen.
What it means for a circuit. When a provider without its own fiber at your address sells you a service, it often buys the local connection wholesale from the incumbent, sometimes called an off-net or Type II circuit, and connects it to its own network. The incumbent’s construction schedule, repair process and conduit routes then become part of your service.
When it matters for buyers
- Ordering connectivity at a new site, when lead time depends on whether the incumbent or another provider already has facilities in the building.
- Designing for resilience. Circuits from different brands can share the incumbent’s conduit, building entrance or central office. Ask for documented path diversity.
- Copper retirement and POTS lines. Incumbents are retiring copper and analog POTS service in many areas, which affects alarm lines, fax, elevator phones and DSL. Retirement follows regulatory notice processes; check with the carrier, and with counsel or the authority having jurisdiction for life-safety lines.
- Escalating outages, when knowing who owns the failed segment speeds up repair.
- Negotiating, since incumbents, competitors and resellers often price the same address differently.
Questions to ask vendors
- Whose network provides the last mile to this address: yours, the incumbent’s or another carrier’s?
- Is the building on-net, and if not, what construction is needed and how long will it take?
- If we buy a second circuit, will it use a different building entrance, conduit and central office? Will you document that?
- Who handles repair for the local segment, and how is escalation handled when the incumbent is at fault?
- Are any of our current copper or analog services scheduled for retirement, and what notice will we receive?
- What replacement options do you offer for lines affected by copper retirement?
If copper retirement is affecting your sites, our POTS replacement overview covers the common options.
How it differs from an ILEC
The terms overlap but are not interchangeable. RBOC refers to the seven regional holding companies created at the Bell System breakup, and by extension their successors. The local service and network belonged to the Bell operating companies they owned. ILEC is a regulatory role: the company that was the incumbent local phone provider in a given area when local competition opened up. A Bell operating company, or its successor, is the ILEC in the traditional territory it still serves, but hundreds of independent phone companies are ILECs too, and some former Bell territories are now run by companies that were never Bell companies. RBOC also differs from an interexchange carrier (IXC), the historical term for long-distance carriers such as AT&T after the breakup.
Problems this helps with
- Our provider says the local phone company owns the last mile to our building
- Two circuits from different carriers failed at the same time
- The phone company is retiring the copper lines at our sites
- Confused by ILEC, CLEC and RBOC on quotes and contracts